You were counting on your long-term disability insurance to protect your income when illness or injury prevented you from working.
Now Canada Life has denied your claim, stopped your monthly payments, or told you that you should be able to return to work.
Your medical condition may not have improved. You still have treatment appointments, household expenses, and a family depending on you.
And suddenly, the financial support you were counting on is uncertain.
At Hilborn and Konduros Lawyers, Rob Konduros helps Ontario residents challenge denied and terminated long-term disability claims, including disputes involving Canada Life.
With nearly 40 years of litigation experience, Rob provides direct, personal legal representation to clients throughout Ontario.
Whether you have just received a denial letter, are approaching the 24-month change-of-definition review, or have already lost your benefits, you can seek legal advice before deciding what to do next.
Canada Life Denied Your Long-Term Disability Claim. What Can You Do?
If Canada Life denies or terminates your long-term disability (LTD) benefits in Ontario, you may be able to challenge the decision through an internal appeal or legal proceedings. Your options depend on your insurance policy, the reasons for the denial, your medical and occupational evidence, and applicable deadlines. An Ontario long-term disability lawyer can review your claim and help determine the appropriate next steps.
A denial letter is Canada Life’s decision about your claim. It does not necessarily mean the decision is legally correct.
Before submitting another appeal, agreeing to return to work, or accepting a lump-sum settlement, it is important to understand why your benefits were refused and whether you remain entitled to coverage under your policy.
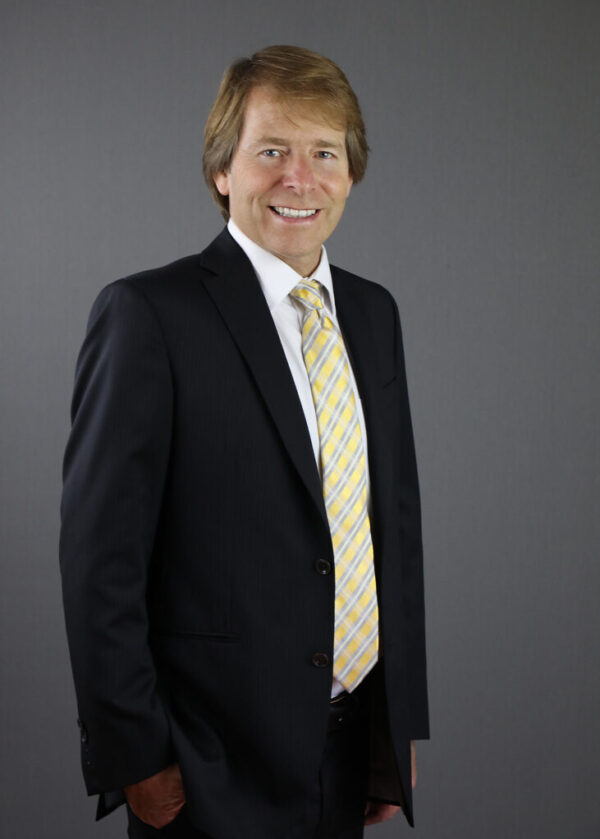
When Canada Life denies your long-term disability claim or cuts off your benefits, you may suddenly find yourself worrying about how you’ll pay your bills and support your family, even though your medical condition still prevents you from working.
I understand how difficult it is to rely on disability insurance for financial protection and then face a denial when you need that support most.
With decades of experience handling disability and insurance disputes in Ontario, I help people challenge unfair decisions and pursue the benefits they’re entitled to receive under their policies.
You deserve to understand your rights before making your next decision.
For a no-obligation chat, call 519 658 6341
– Rob Konduros, Personal Injury & Long-Term Disability Lawyer
Understanding Canada Life Long-Term Disability Coverage in Ontario
Canada Life provides disability insurance through employer-sponsored group benefit plans and individual insurance products.
The coverage you receive depends on your specific insurance contract.
Some Ontario workers receive Canada Life LTD coverage through their employers. Others purchase individual disability insurance to protect their income independently.
These policies may have different eligibility requirements, disability definitions, benefit amounts, and exclusions.
What Does Your Canada Life Disability Policy Cover?
Your insurance policy may address:
-
Definition of disability: The medical and occupational requirements you must satisfy to qualify for benefits.
-
Elimination period: The waiting period before long-term disability payments can begin.
-
Monthly benefit amount: The portion of insured earnings payable, subject to the policy’s limits and conditions.
-
Change of disability definition: Whether the test for continued eligibility changes after a specified period.
-
Benefit offsets: Other income, such as CPP Disability benefits, that may reduce LTD payments under your contract.
-
Exclusions and limitations: Circumstances in which your coverage may be restricted.
-
Rehabilitation and return-to-work provisions: Requirements or benefits relating to recovery and attempts to resume employment.
-
Recurrent disability provisions: Rules governing a disability that returns after an attempted return to work.
Your policy wording matters.
Two Ontario employees covered by Canada Life may have different eligibility requirements, even when they have similar medical conditions.
Rob can review your insurance contract and explain which provisions are relevant to your claim.
Why Are Canada Life Long-Term Disability Claims Denied or Terminated?
Canada Life evaluates disability claims using medical and functional information, occupational requirements, and the terms of the applicable policy.
Disputes can arise when the insurer concludes that the available evidence does not establish entitlement to benefits.
Common issues in long-term disability disputes include the following.
1. Insufficient Medical Evidence
Your doctor may confirm that you have a serious medical condition, but Canada Life may conclude that your medical records do not adequately establish why you cannot work.
A diagnosis identifies your condition. Your claim may also require evidence explaining how that condition affects your ability to perform occupational duties.
For example, medical information may need to describe restrictions involving concentration, memory, physical endurance, attendance, or the ability to complete tasks consistently.
2. Disagreement About Your Ability to Work
Canada Life may conclude that you are capable of returning to your previous occupation or performing another type of work.
Your lawyer can review whether that conclusion accurately reflects your medical limitations and the disability definition in your policy.
3. The Change From Regular Occupation to Gainful Employment
Some Canada Life group disability policies use an initial definition based on your regular occupation and a later definition based on your ability to engage in gainful employment.
This change can create disputes when the insurer concludes that you can perform another suitable occupation.
The applicable test and timing depend on your specific contract.
4. Mental Health or Invisible Disability Claims
Depression, anxiety, PTSD, fibromyalgia, chronic pain, and fatigue-related conditions can significantly affect a person’s ability to work.
These conditions may require detailed evidence showing how symptoms interfere with regular occupational demands.
Medical imaging or laboratory tests may not fully explain the functional effects of every condition.
5. Disagreements About Treatment or Rehabilitation
Your policy may contain requirements relating to reasonable medical treatment, rehabilitation, or cooperation with the claims process.
Canada Life may raise concerns about missed appointments, treatment recommendations, or participation in rehabilitation programs.
However, the circumstances matter. A recommended treatment may be unavailable, ineffective, medically unsuitable, or inappropriate for a particular claimant.
6. Insurer-Arranged Medical Assessments
Canada Life may request medical assessments or additional information as permitted by the policy.
Disagreements can arise when an insurer-arranged assessment reaches conclusions that differ from those of your treating healthcare providers.
Your lawyer can assess the evidence, including whether the assessment addresses your actual occupational limitations.
7. Policy Exclusions and Eligibility Conditions
Some disability policies contain pre-existing condition exclusions, coverage requirements, or restrictions relating to employment status.
Whether an exclusion or limitation applies depends on the precise policy language and facts.
A denial based on one of these issues does not automatically establish that Canada Life’s decision is correct.
An experienced disability lawyer can examine the insurer’s reasoning and the evidence supporting your entitlement to benefits.
How Rob Konduros Can Help With Your Canada Life Disability Claim
Challenging an insurance company while dealing with a serious medical condition can be exhausting.
Rob’s role is to help you understand your legal rights, assess the evidence, and pursue an appropriate resolution.
Review Your Canada Life Insurance Policy
Rob examines the relevant policy provisions, including the disability definition, coverage requirements, exclusions, and applicable deadlines.
Examine the Denial or Termination Decision
He reviews Canada Life’s stated reasons and evaluates whether they are supported by the contractual requirements and available evidence.
Assess Medical and Occupational Evidence
Rob considers whether the medical information adequately explains your functional restrictions and their effect on your occupational duties.
Identify Additional Evidence That May Help
Depending on the circumstances, further medical records, specialist opinions, or vocational evidence may be appropriate.
Explain Your Appeal and Litigation Options
Rob assesses whether an internal appeal, negotiation, lawsuit, or another legal process is appropriate and explains the risks and potential benefits.
Deal With Canada Life on Your Behalf
If you retain the firm, Rob can handle legal correspondence, negotiations, and litigation where appropriate.
Pursue the Benefits You May Be Entitled to Receive
Depending on the case, possible outcomes may include payment of past-due benefits, reinstatement of ongoing payments, or a negotiated lump-sum settlement.
The appropriate remedy depends on the evidence, policy terms, and circumstances. No particular result can be guaranteed.
The goal is to pursue a fair resolution while giving you the information you need to make confident decisions about your future.
Why Choose Rob Konduros for Your Canada Life LTD Claim?
Nearly Four Decades of Ontario Litigation Experience
Robert Konduros graduated from Osgoode Hall Law School in 1986 and has practised litigation for nearly four decades.
His work includes disability insurance disputes, personal injury, employment matters, and insurance litigation.
He has extensive experience appearing before Ontario courts, including the Superior Court of Justice, Divisional Court, and Court of Appeal for Ontario.
Former Chairperson of the CPP Disability Benefits Tribunal
Rob previously served as Chairperson of the Canada Pension Plan Disability Benefits Tribunal.
This background contributes to his understanding of medical evidence, functional restrictions, and disputes about a person’s ability to work.
CPP Disability and private LTD insurance claims have different legal requirements. Rob assesses each case under the rules and contract that apply to it.
Work Directly With Your Lawyer
At Hilborn and Konduros, your case receives personal attention from Rob.
You can discuss your concerns directly with the lawyer handling your claim, ask questions, and receive explanations in straightforward language.
You deserve to understand the decisions being made about your case.
No Upfront Legal Fees for Qualifying Claims
Hilborn and Konduros offers contingency-fee representation for qualifying disability claims.
This generally means legal fees are payable from a successful recovery instead of being charged upfront.
The applicable written agreement explains the fee percentage, disbursements, taxes, and other financial obligations before you decide to retain the firm.
Local Access and Ontario-Wide Representation
Hilborn and Konduros Lawyers is based in Cambridge, Ontario, and represents clients throughout the province.
Telephone and remote consultations are available. Home or hospital visits may also be arranged when appropriate for clients who cannot travel.
When your disability income is at risk, you deserve clear advice, personal attention, and experienced legal representation.
Request a Free Canada Life LTD Case Review
Canada Life Long-Term Disability Lawyer Serving Cambridge and Across Ontario
Hilborn and Konduros Lawyers represents Ontario residents dealing with denied or terminated disability insurance benefits.
The firm assists clients in Cambridge, Kitchener, Waterloo, Guelph, Hamilton, Burlington, Oakville, Mississauga, Brampton, Toronto, London, Barrie, Ottawa, Windsor, and other Ontario communities.
Testimonials
Long-Term Disability Lawyer in Ontario
Robert Konduros of Hilborn and Konduros Lawyers in Ontario has fought insurers on long-term disability denials for 38+ years and is a former Chairperson of the Canada Pension Plan Disability Benefits Tribunal, representing claimants on a contingency-fee basis with no upfront cost.
38
Years of Experience
$0
Upfront Costs
120+
Positive Reviews
Start with a Free Case Review
Long-Term Disability Posts
 Employer-Paid vs. Employee-Paid Long-Term Disability Premiums: How Who Pays Affects Whether Your Benefits Are Taxable
Learn how employer-paid, employee-paid and shared LTD premiums affect whether long-term disability benefits are taxable in Manulife vs. Canada Life vs. RBC. How Long-Term Disability Claims Compare in Ontario
Compare Manulife, Canada Life and RBC long-term disability claims in Ontario, including claim forms, medical evidence, deadlines, appeals and policy Proving Invisible Disabilities in Ontario: Fibromyalgia, Chronic Pain, and Long-Term Disability Claims
Learn how to strengthen an Ontario Long-Term Disability claim for fibromyalgia or chronic pain using medical, functional, work, and reliability